What's the best budgeting app for irregular income?
When your pay jumps around, the app matters less than one rule: never budget money you don't have yet.
The best budgeting app for irregular income is YNAB, because it only lets you budget money that's already in your account. Monarch is the pick if you want something looser, with rollovers and a simpler Flex budget. EveryDollar suits people who plan check by check, and Goodbudget works if you like envelopes.
How do the budgeting apps compare for irregular income?
Each one handles a lumpy month differently, and that difference is the whole decision.
| App | How it handles variable income | Platforms | Price |
|---|---|---|---|
 YNAB | Zero-based. You can only assign money you've received | iPhone, Android, web | $14.99/mo or $109/yr, 34-day trial |
 Monarch | Flex budget (Fixed, Flex, Non-monthly) with rollovers both ways | iPhone, iPad, Android, web | $14.99/mo or $99.99/yr, 7-day trial |
 EveryDollar | Zero-based, plus Paycheck Planning by pay date (Premium) | iPhone, Android, web | Free manual tier; Premium $17.99/mo or $79.99/yr |
 Goodbudget | Envelopes you fill each time money lands | iPhone, Android, web | Free (20 envelopes); Premium $10/mo or $80/yr |
 Hinder | Doesn't plan income. Locks spending apps when you pass a monthly limit | iPhone (iOS 16+) | Free download, 1-week trial, then subscription |
YNAB- How it handles variable income
- Zero-based. You can only assign money you've received
- Platforms
- iPhone, Android, web
Monarch- How it handles variable income
- Flex budget (Fixed, Flex, Non-monthly) with rollovers both ways
- Platforms
- iPhone, iPad, Android, web
EveryDollar- How it handles variable income
- Zero-based, plus Paycheck Planning by pay date (Premium)
- Platforms
- iPhone, Android, web
Goodbudget- How it handles variable income
- Envelopes you fill each time money lands
- Platforms
- iPhone, Android, web
Hinder- How it handles variable income
- Doesn't plan income. Locks spending apps when you pass a monthly limit
- Platforms
- iPhone (iOS 16+)
How does Monarch compare with other budgeting apps for irregular income?
Monarch is the most comfortable of the bunch, but it's less strict than YNAB about spending money before it arrives.
Its default mode is Flex budgeting, which sorts spending into three buckets. Fixed is rent and the phone bill. Non-monthly is stuff like car registration, which Monarch splits across the next 12 months for you, so a $480 bill becomes $40 a month. Flex is everything you actually decide on: groceries, restaurants, the random Target run. You watch one Flex number instead of twenty categories, which is a real relief when you're already tracking invoices.
The feature that matters most for variable pay is rollovers. Underspend a category and the leftover carries into next month. Overspend it and the deficit carries forward too, so you pay it down instead of pretending it didn't happen. That smooths out the lumpy months reasonably well.
Here's the catch. Monarch lets you set a budget for the month whether or not the money is in the bank. If you plan March around a client invoice that pays in April, Monarch won't stop you. YNAB will. So the honest comparison is: YNAB is better at keeping you from spending money you haven't earned, and Monarch is better at showing you the whole picture with less daily effort. It runs $14.99 a month or $99.99 a year after a 7-day trial, on web, iPhone, iPad, and Android. More on where it falls short in our Monarch alternatives roundup.
Is YNAB good for irregular income?
Yes, it's arguably the best tool ever built for it, as long as you'll put in the work.
YNAB doesn't ask what you expect to earn. You enter money when it actually arrives, it lands in Ready to Assign, and you give each dollar a job until that number hits zero. Try to assign $800 when you only have $500 and Ready to Assign turns red. That's exactly the guardrail you want when a client is 45 days late.
The long game is what YNAB calls spending last month's money. You build enough of a cushion that this month runs entirely on what you earned last month, and the timing of any one payment stops mattering. For freelancers that's the whole goal.
The downsides are real, though. It costs $14.99 a month or $109 a year after a 34-day trial, and the method needs you to show up every time money comes in. People who skip a few weeks tend to drift away. If that sounds like you, read the YNAB alternatives before you commit.
What's the best budgeting app for freelancers?
YNAB for most freelancers, Monarch if you want less upkeep, and EveryDollar if your checks land on predictable dates.
 YNAB
Best if payments arrive whenever clients feel like it. Because you only budget what's landed, it doesn't care if you get paid once a month or six times. Every deposit is just more money to assign.
 Monarch
Best for seeing everything at once. If you juggle a business checking account, a personal one, and a few cards, Monarch pulls them together and rollovers absorb the swings. Just budget off money you've actually been paid. It won't enforce that for you.
 EveryDollar
Best for gig workers with several checks a month. Paycheck Planning, a Premium feature, lets you set the date each check arrives and line bills up against it. Ramsey's own advice for irregular income is to enter a conservative, low estimate for each check and update it when the real number shows up. The free tier is zero-based but manual; Premium adds bank sync at $17.99 a month or $79.99 a year, after a 14-day trial.
 Goodbudget
Best if you think in envelopes. Every time a payment lands, you fill envelopes in priority order until the money runs out. Rent first, fun last. The free plan covers 20 envelopes on one account and two devices. Premium, at $10 a month or $80 a year, adds unlimited envelopes and automatic bank sync. For the bigger field, see our best budgeting apps of 2026.
How do you budget when your income changes every month?
Pick a number you can count on, live on it, and park everything above it.
- Find your floor. Look at the last six to twelve months and take your lowest month, or at least a number well under the average. Budget off that, never off your best month.
- Cover the must-haves first. Rent, utilities, insurance, minimum debt payments, and taxes if you're self-employed. Fund those from the first dollars in.
- Send the extra to a buffer. Anything above your floor goes into a separate savings account. Don't look at it as bonus money. It's next month's rent.
- Pay yourself a salary. Once the buffer holds a full month of expenses, move the same amount into checking on the same day every month. Now you're budgeting a steady paycheck, and any app works.
- Cap the fun categories. The floor only works if a big month doesn't quietly raise your spending. More on that next.
How do you stop overspending in a good month?
Put a hard limit on the categories that balloon when you're flush, because no budgeting app will stop you on its own.
Here's the part nobody warns freelancers about. The lean months are stressful, but the good months are where the damage happens. A big invoice clears, you feel rich, and suddenly there are three DoorDash orders and an Amazon cart that would have been out of the question in February. YNAB and Monarch will both show you the overspend afterward. Neither one gets in the way.
That's the gap Hinder fills, and to be clear, it isn't an income planner. It doesn't forecast pay, roll budgets over, or track net worth. It connects to your bank through Plaid (or you log transactions by hand), you set a monthly limit per category or per app, and it warns you at 80%. At 100% it uses iOS Screen Time to lock the spending apps you've connected. You can override the lock, but it takes some deliberate friction, which is the point.
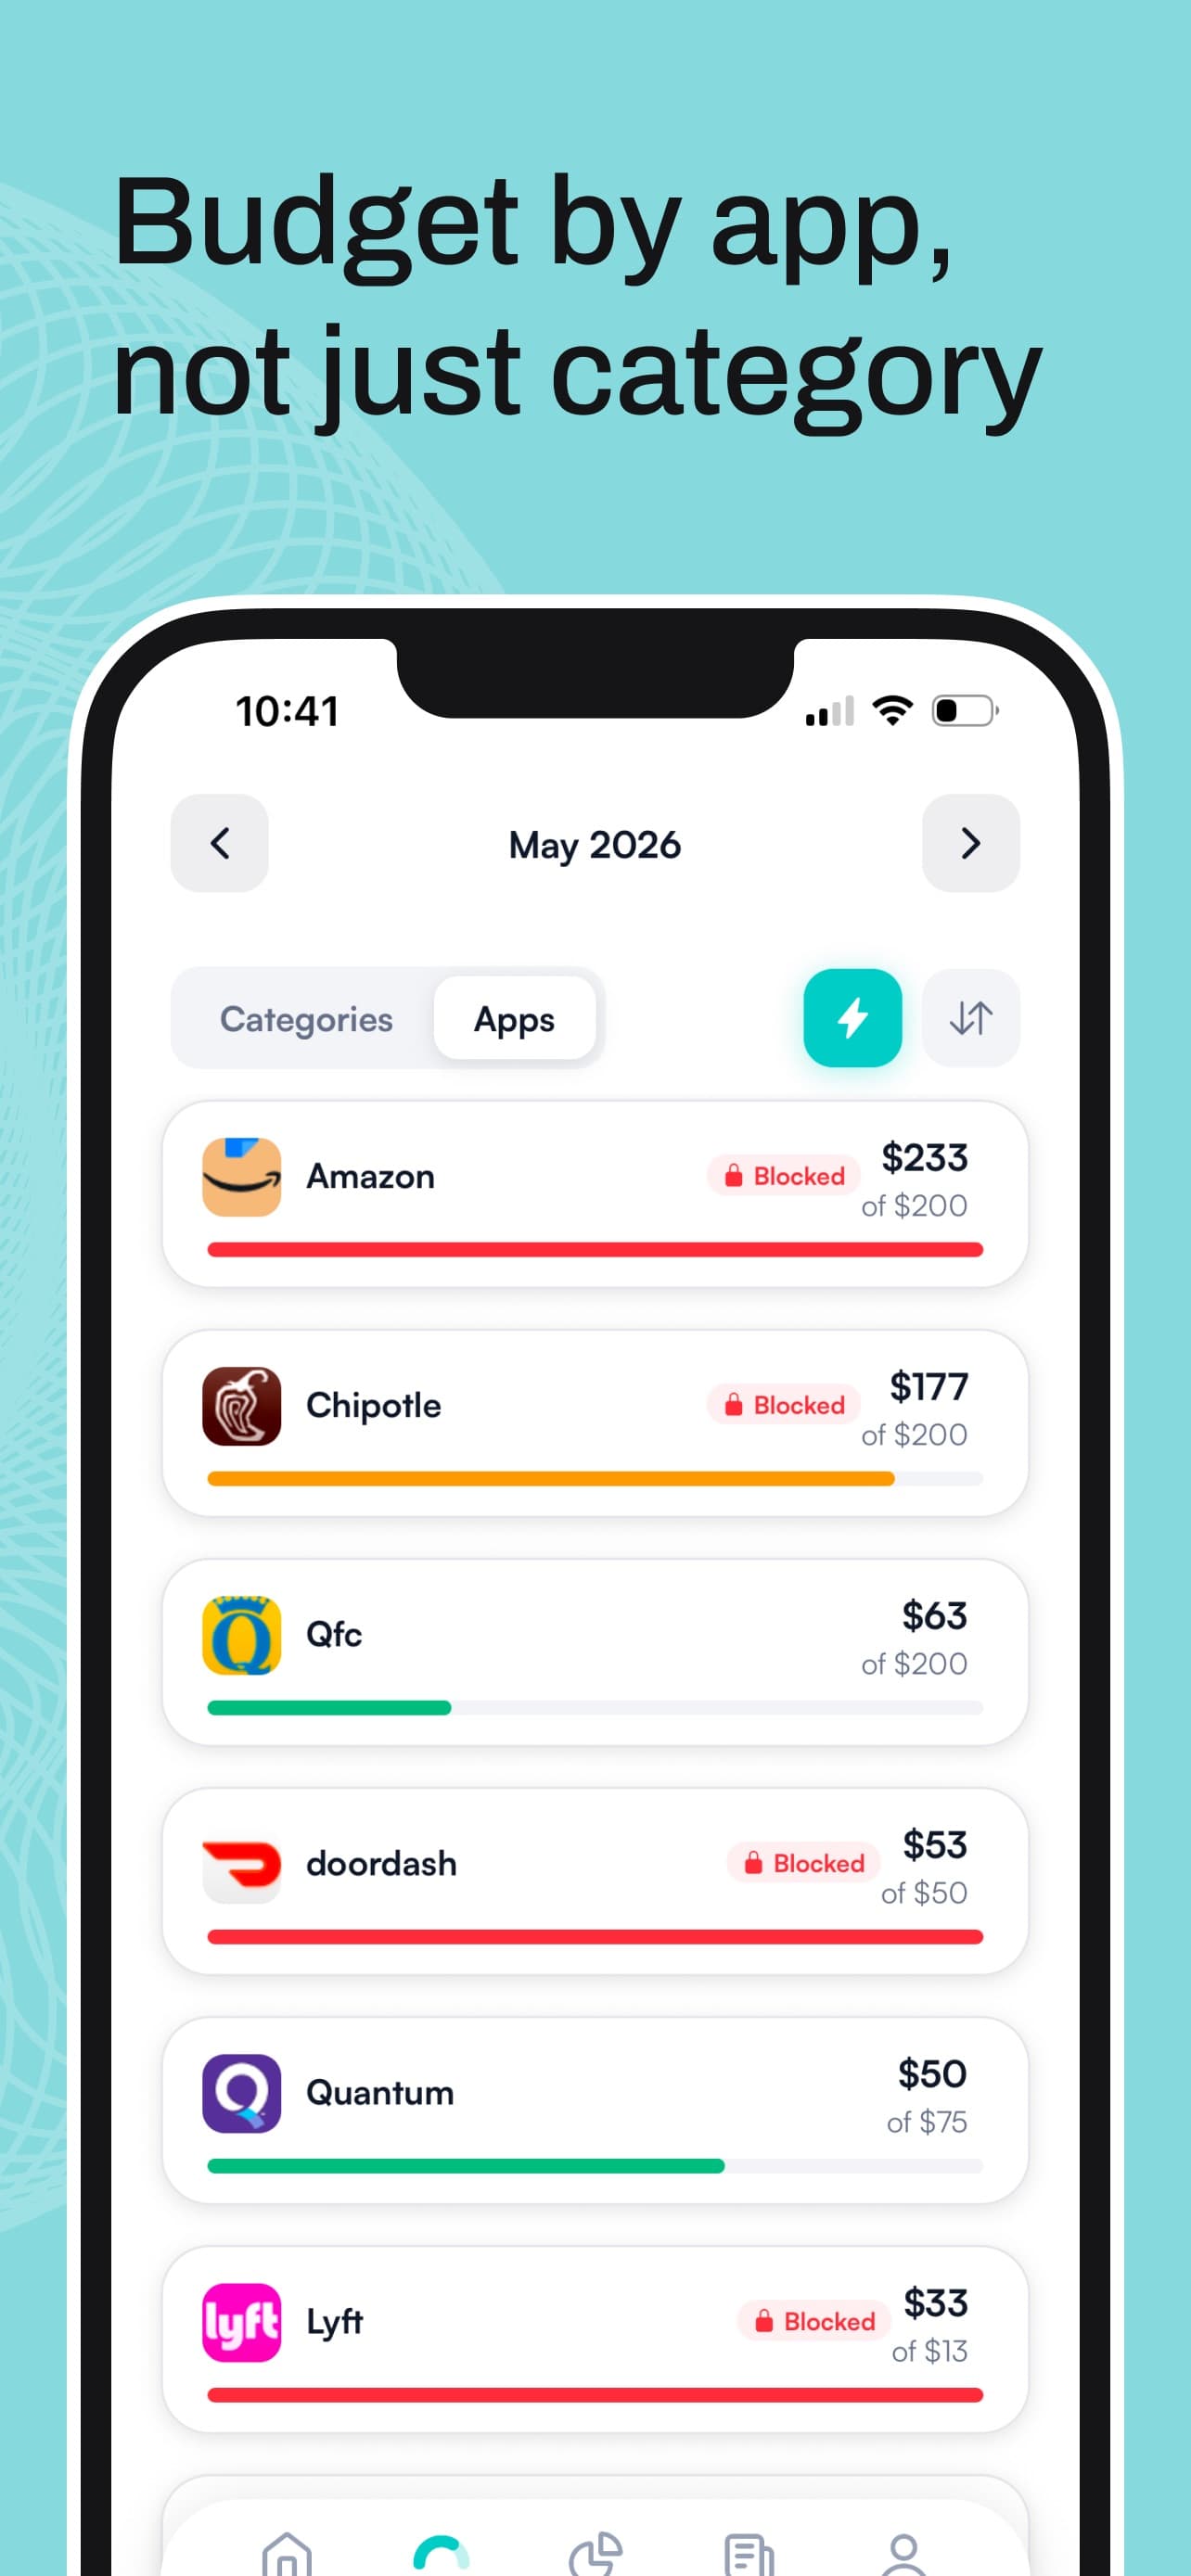
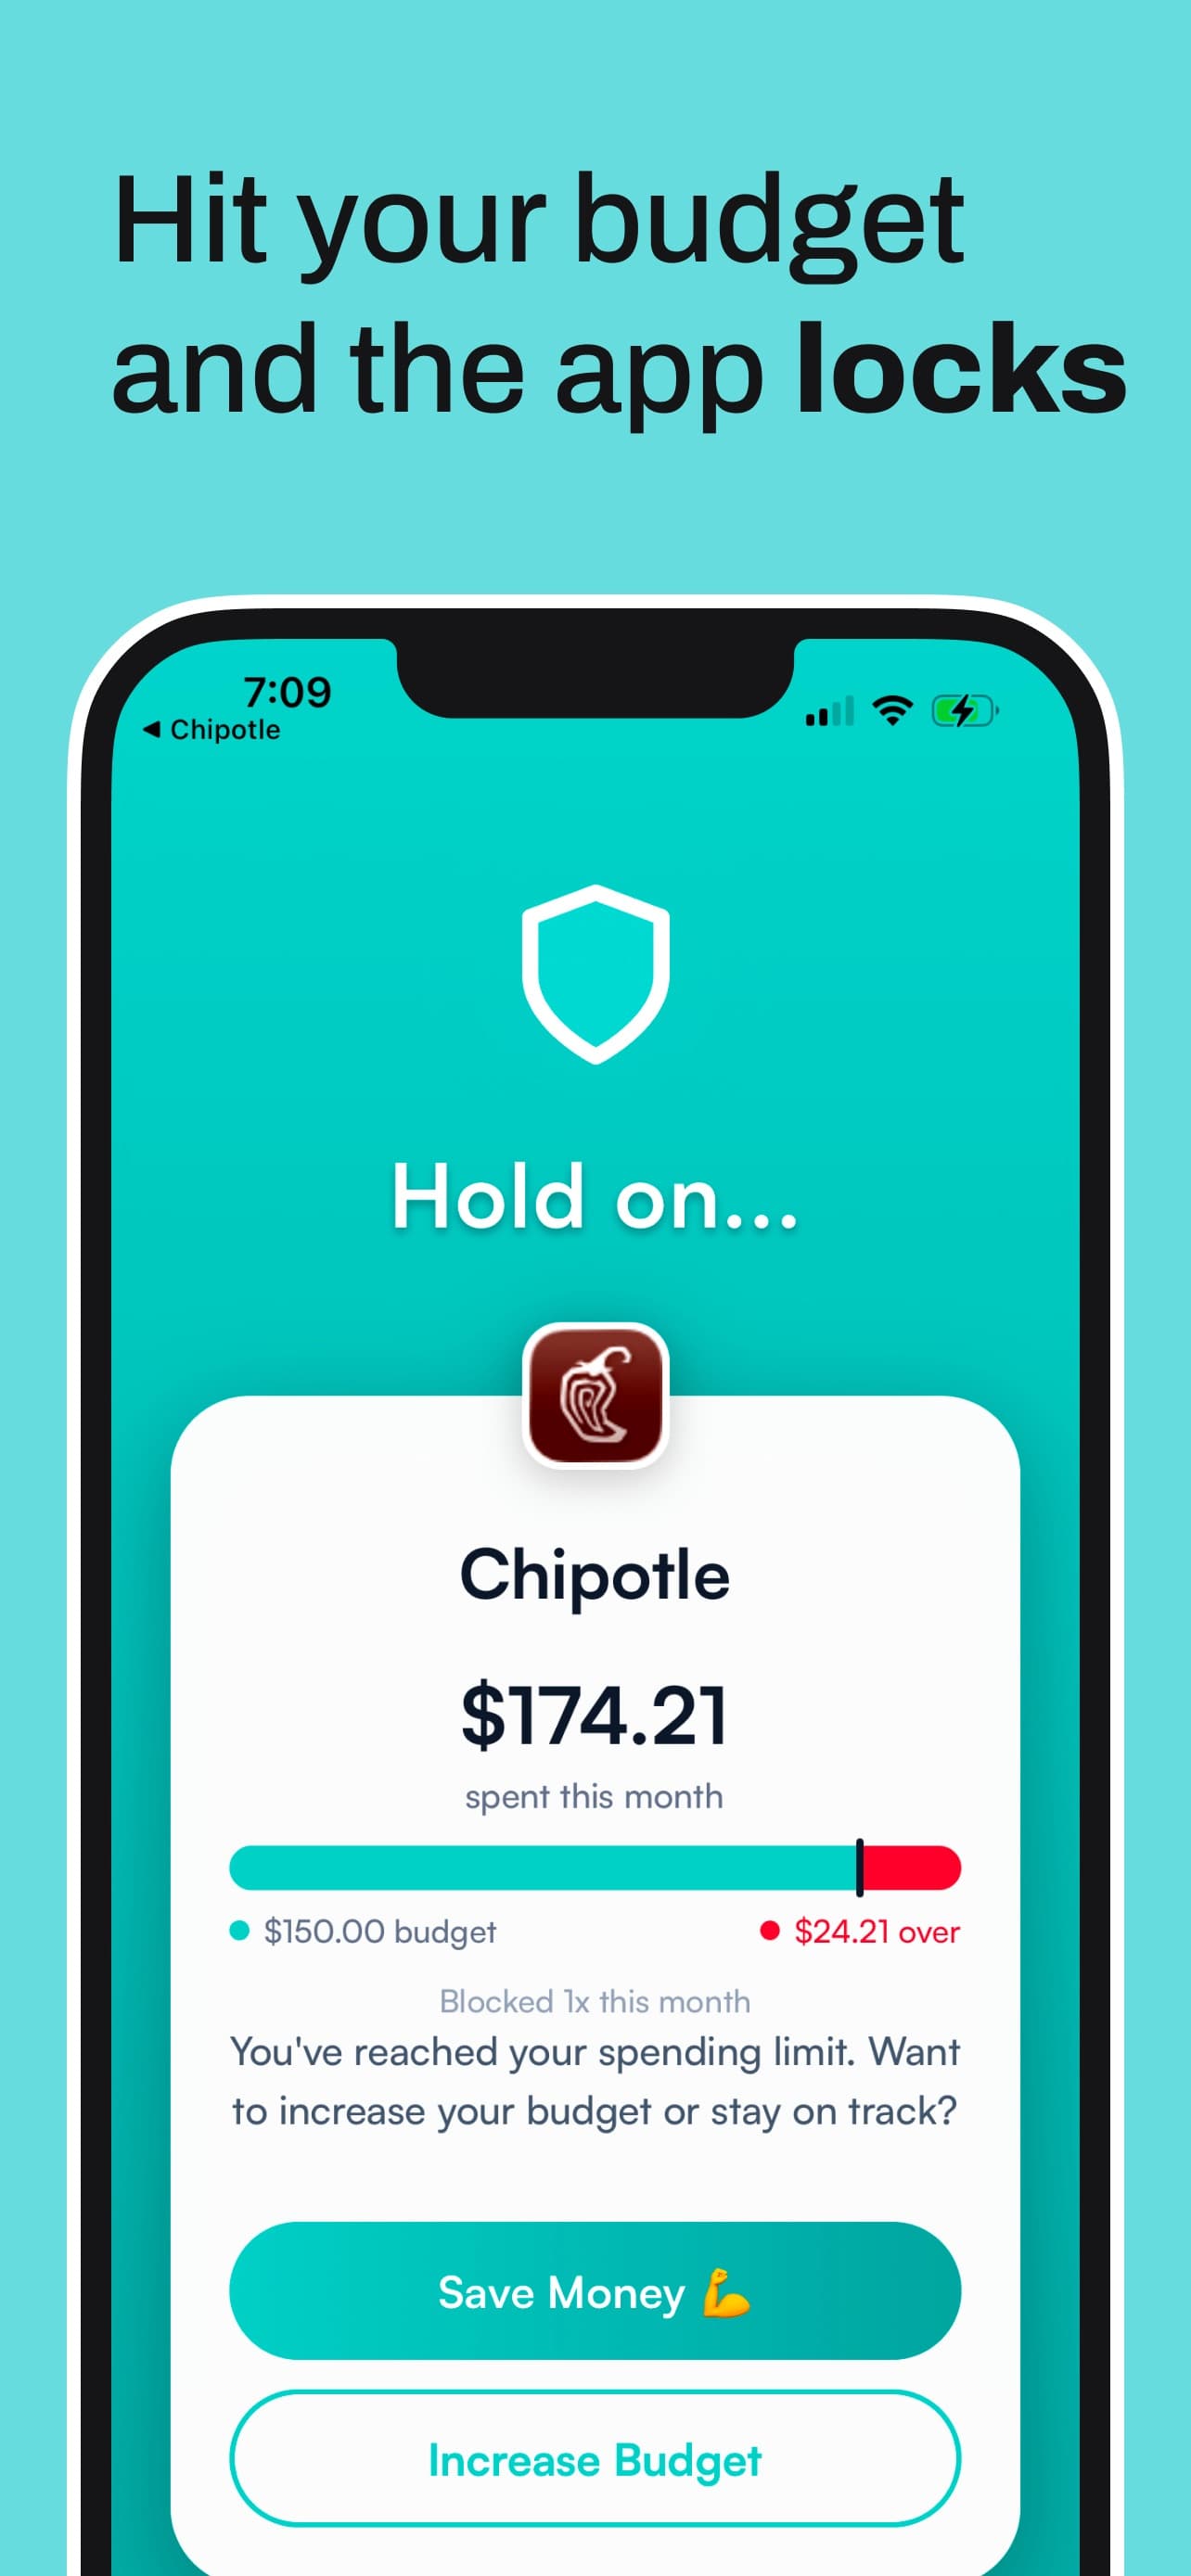
So the setup that works for a lot of irregular earners is two apps. YNAB or Monarch decides what the money is for. Hinder makes sure the delivery and shopping lines don't eat the buffer in a good month. There are per-app no-spend streaks too, if you like watching a counter climb. Our YNAB vs Hinder and Monarch vs Hinder breakdowns cover how the pairing works. Hinder is iPhone only (iOS 16 and up), free to download with a one-week free trial, then a subscription.
Common questions
Is YNAB or Monarch better for irregular income?
YNAB, for most people with lumpy pay. It only lets you assign money you've already received, so a slow month can't be planned around income that never shows up. Monarch is better if you'd rather set a simple Flex budget, use rollovers to carry surpluses and deficits forward, and see all your accounts in one place.
What is the best free budgeting app for irregular income?
EveryDollar's free tier lets you build a zero-based budget and enter transactions by hand at no cost. Goodbudget's free plan gives you 20 envelopes on one account across two devices, which is enough to fill envelopes each time a payment lands. Bank sync costs extra on both.
How much should I budget each month if my income changes?
Budget off your lowest recent month, or off last month's actual income, never your best month or your hopeful average. Anything earned above that goes to a buffer account. Once the buffer holds a full month of expenses, you can pay yourself the same amount every month from it.
Can Hinder budget my irregular income?
No. Hinder doesn't plan income, roll budgets forward, or forecast cash flow. It does the other half: you set monthly limits per category and per app, it warns you at 80%, and it locks the connected spending apps at 100% using iOS Screen Time. Most irregular earners pair it with YNAB or Monarch.
What's the best budgeting app for freelancers and gig workers?
YNAB, if you can commit to giving every dollar a job as payments arrive. It works the same whether a client pays on the 3rd or the 27th. Monarch suits freelancers who want lighter upkeep and a full view of every account, and EveryDollar Premium's Paycheck Planning helps if you get several checks a month on known dates.